Can I Use EIN Instead of SSN? It depends what the form is asking
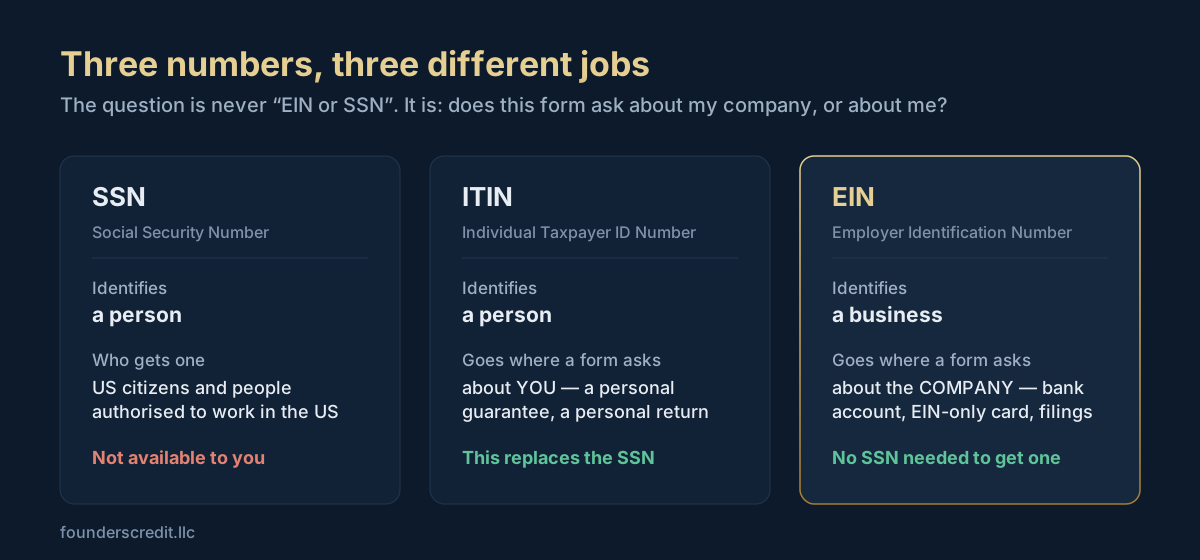
Short version: for anything about your company, yes. For anything about you, no — and the thing that goes there instead is an ITIN, not an EIN. Almost every problem non-US founders run into with US banks and card issuers comes from not knowing which of those two situations they are in. Here is how to tell them apart before you fill in the form.
What each number actually identifies
They are not two versions of the same thing, and that is the root of the confusion.
An SSN identifies a person. It is issued to US citizens and to certain people authorised to work in the United States.
An EIN identifies a business entity. The IRS issues it to your LLC or corporation so the company can be taxed, employ people and open accounts in its own name. It says nothing about you.
An ITIN identifies a person who cannot get an SSN. It exists precisely for the gap you are standing in.
So the question is never really “EIN or SSN”. It is: is this form asking about my company, or about me? Answer that and the rest follows.
Where an EIN does work instead of an SSN
Everywhere the subject is the company.
- Opening a US business bank account. The account belongs to the LLC, so the EIN is the tax ID it is opened under. Mercury and Relay both work this way for non-resident-owned LLCs.
- EIN-only corporate cards. Ramp, Brex and similar underwrite the business against its bank balance and revenue rather than your personal credit, so no personal number is needed at all.
- Business tax filings. The LLC's federal returns are filed under its EIN.
- Invoicing US clients and the W-9 your client asks you to complete for the company.
- Business credit reporting. A D-U-N-S number and Net-30 vendor accounts build a file against the EIN, not against you.
This is genuinely most of what a founder needs day to day, which is why plenty of people run a US company for years having never held a personal US number.
Where it does not, and what goes there instead
Everywhere the subject is you.
The clearest case is a personal guarantee. Traditional business credit cards from Amex, Chase and Capital One ask you to stand behind the company's debt personally. That application has a line for your taxpayer identification number, and an EIN does not satisfy it, because the EIN is not about you. What goes there is an ITIN.
The same applies to a personal US bank account, a personal credit file at Experian, Equifax or TransUnion, and a personal US tax return.
This is the single most common place founders lose weeks: they get the EIN, assume they are done, apply for an Amex Business card, and are declined — not because the business was weak, but because the form was asking a question the EIN cannot answer. The fix is the ITIN, and getting one takes its own time, which is why it belongs earlier in the sequence than most people put it.
Can an EIN be a social security number? No, and the difference matters
Both are nine digits, which is where the idea comes from. They are formatted differently (an EIN reads 12-3456789, an SSN 123-45-6789) and they are issued by different processes for different subjects.
An EIN cannot be used as personal identification, cannot be used to work in the United States, and does not build your personal credit history. Any service implying otherwise is selling you a misunderstanding, and it is worth being suspicious of one that does — the same vagueness tends to show up in what they promise about card approvals.
What is true, and useful, is narrower: you do not need an SSN to get an EIN. As a non-resident you file paper Form SS-4 and write “Foreign” on the line asking for the responsible party's taxpayer ID. The ITIN has its own form, Form W-7. See how to get an EIN without an SSN.
The credit card question people are really asking
Most people typing this are not curious about tax administration. They want a US credit card and have been told they need an SSN they cannot get.
There are two routes, and which one you are on decides whether the EIN is enough:
EIN-only, no personal guarantee. Ramp, Brex and the fintech corporate cards. They underwrite the company's cash, so an EIN and a funded US business account are the whole requirement. This route is open to you today.
Personal guarantee. Amex Business Gold and Platinum, Chase Ink, Capital One Spark. These need a personal taxpayer ID, so an ITIN, plus enough US history behind you to be approved. This route is open later.
Taking them in that order is the point: the first route builds the record that makes the second one possible. Detail in getting a US business credit card with an EIN only.
Can I use EIN instead of SSN? A test for any form
Before you fill in a taxpayer ID field anywhere, ask one question: if this goes wrong, who is on the hook — the company or me?
If the answer is the company, the EIN belongs there. If the answer is you, an EIN will not do and an ITIN will.
It sounds too simple to be useful. It is right almost every time, and it would have saved most of the declines we see.
Frequently Asked Questions
Can I use EIN instead of SSN?
For anything concerning your company, yes: opening a US business bank account, EIN-only corporate cards, business tax filings and business credit reporting all run on the EIN. For anything concerning you personally — a personal guarantee on a credit card, a personal bank account, a personal credit file — no. An ITIN goes there instead.
Can an EIN be a social security number?
No. Both are nine digits, which is where the confusion starts, but they identify different subjects. An SSN identifies a person; an EIN identifies a business entity. An EIN cannot be used as personal identification, does not authorise work in the United States, and does not build your personal credit history.
Do I need an SSN to get an EIN?
No. A non-resident applies for an EIN on paper Form SS-4, writing “Foreign” on the line asking for the responsible party's taxpayer identification number, and faxes it to the IRS international fax number. It typically takes one to four weeks and it is free.
Can I get a credit card with just an EIN?
Yes, but only one kind. EIN-only corporate cards such as Ramp and Brex underwrite the business against its bank balance and require no personal guarantee. Traditional business credit cards from Amex, Chase and Capital One ask you to guarantee the debt personally, and that application needs an ITIN.
If I have an EIN, do I still need an ITIN?
You need one as soon as a form asks about you rather than about the company — in practice, the first time you apply for a card with a personal guarantee or file a personal US return. Because the ITIN takes time to obtain, it is worth starting it before you need it rather than after a decline.
Related Articles
Are you a good fit?
Find out if you are a good fit for the US credit system or the US banking system. See what you would qualify for in about two minutes.
Find out if you're a good fit →Takes 2 minutes · Free